
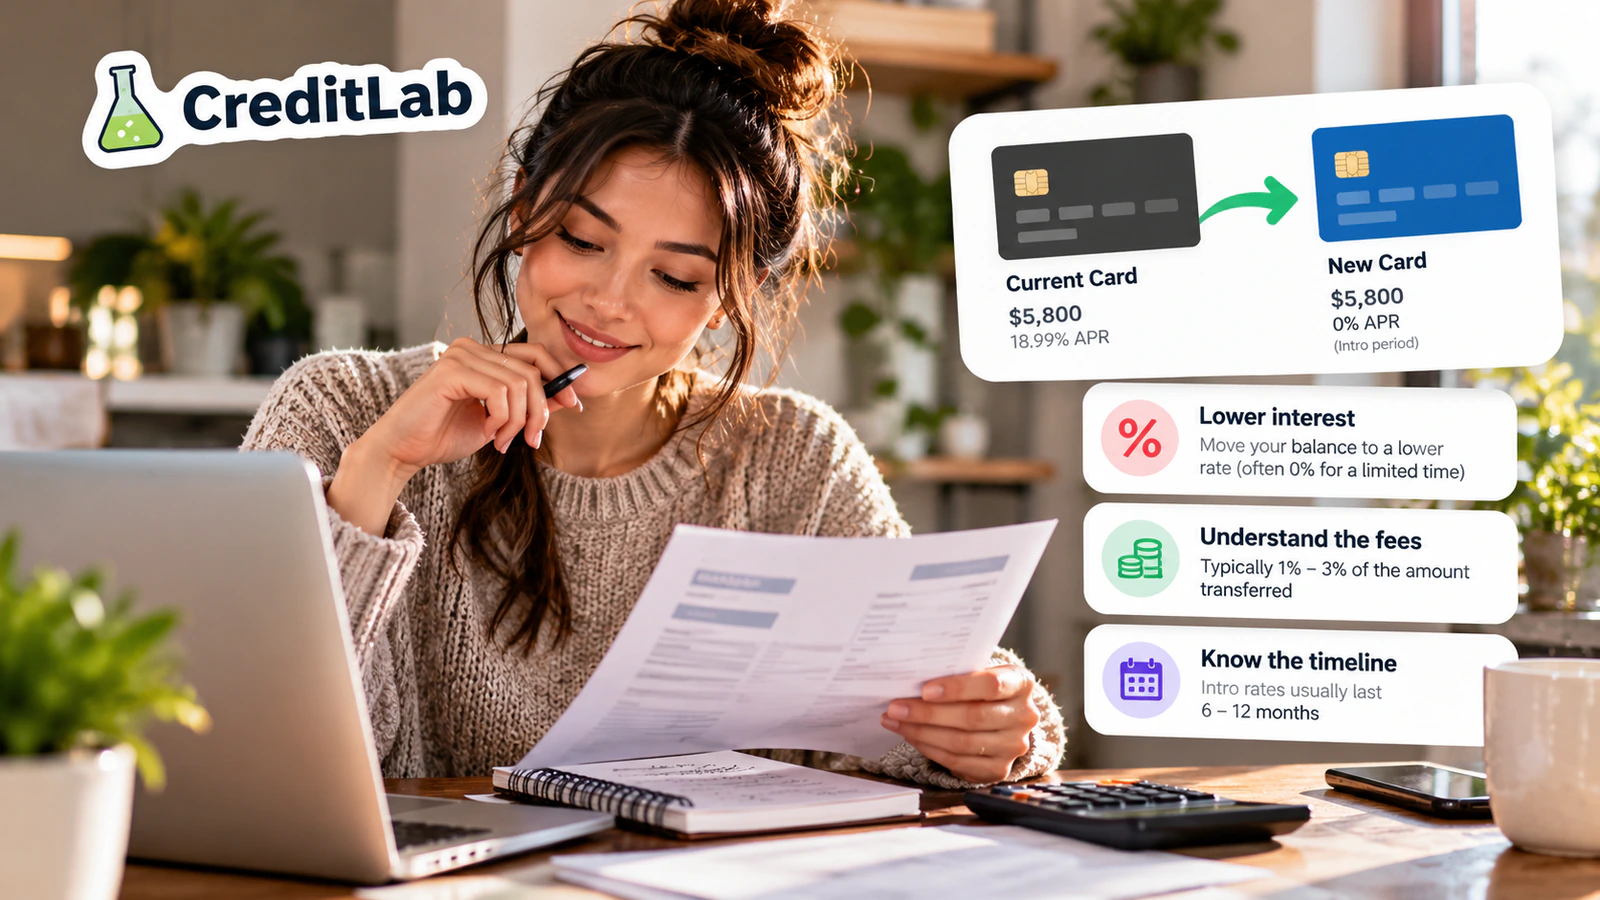
- FCAC says balance transfer promo rates usually last 6 to 18 months, and you can lose the rate if you miss a payment.
- The transfer fee is a percentage of the amount moved: 1% on a $5,000 transfer is $50, and 3% is $150.
- When the promo ends, the leftover balance moves to the card’s cash advance or balance transfer rate, which ranges from 13.99% to 23.99% on the cards in our table.
- Your minimum payment typically goes to the lowest-rate part of your balance, so new purchases on the same card can build interest.
Checked October 2026
How a balance transfer works
The Financial Consumer Agency of Canada (FCAC) describes a balance transfer simply: you move your balance from an old credit card to a new one. The new card pays off the old balance, and you now owe that amount to the new issuer instead.
Most people do it to swap a high interest rate for a low one for a while. Many issuers offer a lower or 0% introductory rate on transferred balances, and FCAC says that promo usually lasts 6 to 18 months.
- Apply for a card with a transfer offerCheck the offer’s rate, length, fee and deadline. Some only apply to transfers made at application or within a set window, such as 90 days after opening.
- Request the transferGive the new issuer your old card number and the amount. Issuers often cap the transfer at part of your limit. CIBC, for example, allows up to 50% of the credit limit on its offer.
- Keep paying the old card until it shows zeroThe transfer can take time to post. A missed payment on the old card still counts against you.
- Pay down the new balance before the promo endsDivide the balance by the number of promo months to get the payment that clears it in time.
What it really costs
A 0% offer is rarely free. FCAC says the transfer fee is usually a percentage of the amount you move. Its own example: moving a $1,000 balance with a 3% fee costs $30. On the offers in our table, fees run from 1% to 3%, with a minimum of $3.50 to $5 per transfer. RBC charges a flat $5 per transfer instead of a percentage.
The second cost arrives when the promo ends. Whatever you still owe moves to the card’s regular rate for balance transfers, which is often its cash advance rate. Scotiabank’s Value card goes to 13.99%, while the Scotia Momentum Visa card goes to 22.99%. A transfer card with a low ongoing rate gives you a softer landing if you don’t finish in time.
How your payments are applied
This is the rule that catches people out. If your new card carries more than one balance, say a transferred balance at 0% and new purchases at 20.99%, FCAC says your minimum payment typically goes to the part with the lowest interest rate. That’s the promo balance.
Anything you pay above the minimum must go one of two ways: to the part of the balance with the highest interest rate, or spread proportionally across the whole balance. Your cardholder agreement says which method your issuer uses.
Worked example: $5,000 at 20.99%
Say you owe $5,000 on a card that charges 20.99%. In the first month alone, interest is about $87.46. To clear the debt in 9 months you’d need to pay about $555.56 a month.
| Where the $5,000 sits | Cost over 9 months | Owing after 9 months |
|---|---|---|
| Stay on the 20.99% card | About $480 in interest | About $480 |
| 0% for 9 months, 1% fee | $50 transfer fee | $0 |
| 0.99% for 9 months, 2% fee | $100 fee plus about $20.72 interest | About $20.68 |
CreditLab arithmetic, interest charged monthly on the remaining balance. Your issuer’s daily interest calculation will differ slightly.
Now say you can only manage $300 a month. After 9 months at 0%, you’d still owe $2,300. If that rolls to 13.99%, interest is about $26.81 a month. At 22.99%, it’s about $44.06 a month. The transfer still saved money, but the job isn’t done.
Run your own numbers with the balance transfer calculator, or use the debt payoff calculator to set a monthly target.
Current balance transfer offers
These are cards in our data that list a balance transfer promotion. Offers have deadlines and conditions, so confirm the terms on the issuer’s page before you apply.
| Card | Promo rate | Length | Transfer fee | Rate after the promo |
|---|---|---|---|---|
| CIBC Select Visa Card | 0% | Up to 10 months | 1% | 13.99% |
| Scotiabank Value Visa Card | 0% | 9 months | 1%, minimum $5 | 13.99% |
| MBNA True Line Mastercard | 0% | 12 months | 3%, minimum $3.50 | 17.99% |
| BMO Blue Rewards World Elite Mastercard | 0% | 12 months | 2% | 23.99% |
| RBC Visa Classic Low Rate Option | 0.99% | 10 months | $5 per transfer | 14.99% |
| BMO Preferred Rate Mastercard | 0.99% | 9 months | See BMO’s terms | 15.99% |
| Scotia Momentum Visa card | 0.99% | 9 months | 2%, minimum $5 | 22.99% |
Checked October 24, 2026. Scotiabank’s offers apply to accounts opened July 2, 2026 to January 3, 2027. RBC’s offer needs an application by November 4, 2026. MBNA’s applies to transfers made within 90 days of opening.
Low-rate cards such as the CIBC and Scotiabank Value cards keep a lower rate after the promo ends. Rewards cards with transfer offers usually jump higher. See all low interest credit cards if you expect to carry a balance past the promo.
Risks to weigh first
- Missed payments. FCAC warns that missing a minimum payment or paying late can raise your rate, cost you the promo rate and hurt your credit score.
- Running the old card back up. If you keep spending on the card you just cleared, FCAC notes that consolidating debt can leave you owing more than before.
- A new application. Applying for credit adds an inquiry to your credit report, and several applications close together can lower your credit score.
- Eligibility rules. Some offers exclude current or recent cardholders. Scotiabank’s, for example, isn’t available if you’ve held a Scotiabank personal credit card in the past 2 years.
If you owe on several cards and loans, a balance transfer is one form of debt consolidation. A line of credit or a consolidation loan can work better when the debt will take longer than a promo period to pay off.
Frequently Asked Questions
What is a balance transfer credit card?
It’s a card that lets you move a balance from another credit card onto it, usually at a 0% or low promotional rate for a set number of months. You pay a transfer fee, and the rate rises when the promo ends.
How much does a balance transfer cost?
Most issuers charge a percentage of the amount moved. On the offers in our table it’s 1% to 3%, sometimes with a $3.50 or $5 minimum. RBC charges a flat $5 per transfer on its Classic Low Rate Option.
How long do 0% balance transfer offers last?
FCAC says promotional rates usually last 6 to 18 months. The offers in our table run 9 to 12 months.
What happens when the promo period ends?
Any remaining balance moves to the card’s regular balance transfer or cash advance rate. On the cards in our table, that’s 13.99% to 23.99%.
Can I lose the promotional rate early?
Yes. FCAC says you may lose a promotional rate if you miss a payment, so set up an automatic minimum payment at the least.
Does my payment go to the transferred balance or my purchases first?
FCAC says the minimum payment typically goes to the lowest-rate part of your balance. Anything above the minimum goes either to the highest-rate part or proportionally across the balance, depending on your issuer.
Does a balance transfer hurt my credit score?
Applying for a new card adds a credit inquiry, and several applications close together can lower your score. Paying the balance down on time can help your score over time.
Do I still make payments during a 0% promo?
Yes. FCAC says you still need to make minimum monthly payments on a transferred balance, and missing one can cost you the promotional rate.
What is the best balance transfer credit card in Canada?
It depends on how fast you can repay. A longer 0% offer suits a big balance. A card with a low rate after the promo, such as 13.99%, suits you if some balance may be left over.
Is a balance transfer the same as a cash advance?
Many issuers treat it as one. RBC and Scotiabank both describe balance transfers as a type of cash advance, which is why the rate after the promo is often the cash advance rate.
Try this next
Sources, checked October 2026
- FCAC: How credit cards work canada.ca
- FCAC: Debt consolidation canada.ca
- FCAC: Paying off your credit card canada.ca
- CIBC: CIBC Select Visa Card cibc.com
- Scotiabank: Scotiabank Value Visa Card scotiabank.com
- Scotiabank: Scotia Momentum Visa Card scotiabank.com
- MBNA: MBNA True Line Mastercard mbna.ca
- RBC: RBC Visa Classic Low Rate Option rbcroyalbank.com
- BMO: BMO Preferred Rate Mastercard bmo.com
- BMO: BMO Blue Rewards World Elite Mastercard bmo.com
General information for Canadians, not financial, tax or legal advice. Rules and menus change, so confirm details with your bank, lender or the Government of Canada. See our methodology.