
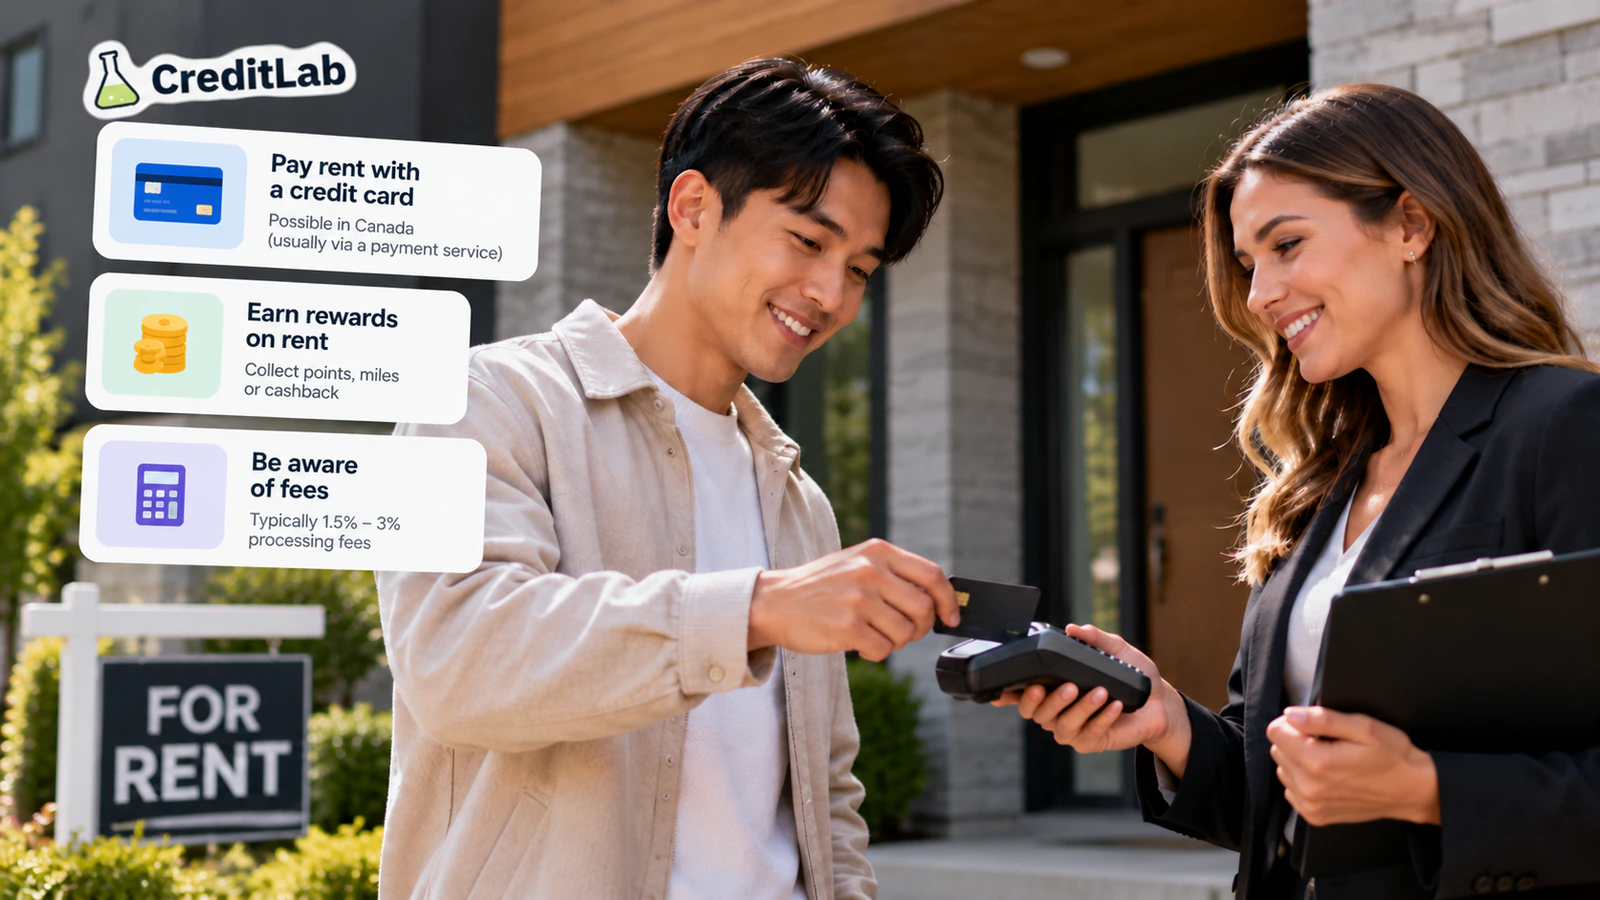
- The clearest case is a welcome bonus: one $2,000 rent payment toward a 10% intro offer earns $200 for a $35 fee.
- Most landlords don’t take cards, so you pay through a service such as Chexy, TenantPay or Letus, which charges your card and pays the landlord by e-Transfer, debit or deposit.
- As of October 2026, Chexy charges 1.75% on Canadian Visa, Mastercard and Amex. TenantPay charges 1.75% on Visa credit and 2.75% on Mastercard credit.
- At a 1.75% fee, a card must return more than 1.75% on rent to come out ahead. On $2,000 rent, a 1% card loses $180 a year.
- Carrying the balance wipes out the gain. One month of interest at 21.99% on $2,000 is about $36.65, more than the fee.
Checked October 2026
Can you pay rent with a credit card?
Yes, but usually not directly. Most landlords take e-Transfer, cheques or pre-authorized debit, not cards. To pay rent with a credit card in Canada, you use a third-party service that charges your card, adds a fee, and sends the rent to your landlord in a form they already accept.
That middle step is what makes it more complicated than paying for groceries. A landlord who accepted cards directly would pay card processing costs on every rent cheque. Few individual landlords set that up. Larger property managers sometimes do, through rent platforms that pass a fee to the tenant.
So the real question isn’t whether you can use a credit card to pay rent. It’s whether the fee is smaller than what your card gives back, and whether you can pay the card off in full every month. This guide works through both with numbers.
How paying rent with a credit card works
You give a rent payment service your card and your landlord’s payment details. The service charges your card, keeps a percentage, and pays your landlord. Your landlord receives an ordinary payment, such as an Interac e-Transfer, a bill payment, a pre-authorized debit or a direct deposit.
There are two models in Canada. In the first, the service works on the tenant side only. You sign up, you add your landlord as a payee, and the landlord keeps getting an e-Transfer as before. Chexy works this way. Its rent page says your landlord “doesn’t need to sign up or know.”
In the second, the service is the landlord’s or property manager’s rent platform. Your building uses it to collect rent, and paying by card is one option inside it. Letus works this way: its terms say tenants may only pay landlords, property managers and other entities that are authorized partners of Letus. TenantPay’s own pages describe both setups, which we cover below.
Either way, the fee is charged to you on top of the rent. Your card statement shows the rent plus the fee, or the rent and the fee as two lines. Your landlord receives the full rent.
- You schedule the paymentEnter the rent amount, due date and how your landlord wants to be paid.
- The service charges your cardChexy, for example, charges your card 4 business days before rent is due.
- The service pays your landlordBy e-Transfer, bill payment, pre-authorized debit or direct deposit, depending on the service and the landlord.
- You pay your card billYour card issuer gives you a grace period on purchases. Pay the statement in full and you pay no interest.
Rent payment services in Canada, compared
Five services that serve Canadian renters publish enough on their own sites to compare: Chexy, Neobanc, Casa, TenantPay and RentMoola, which is now Letus. To run your own rent and card numbers, use our rent payment calculator. Fees below are as of October 2026, from each service’s own pricing page, FAQ or terms.
| Service | Fee on credit card | Cards accepted | How the landlord is paid | Rent reporting |
|---|---|---|---|---|
| Chexy | 1.75% on Canadian-issued cards; 2.5% on international cards | Visa, Mastercard, American Express | Interac e-Transfer, bill payment or pre-authorized debit, on rent day; landlord doesn’t sign up | Opt-in Credit Builder reports to Equifax (described in a June 2024 Chexy article) |
| Neobanc | 2.75% on its homepage; 1.50% to 2.25% in its FAQ | Visa, Mastercard; American Express not supported | Interac e-Transfer; landlord doesn’t sign up | Optional free reporting to credit bureaus (bureau not named) |
| Casa | 1.75% on Canadian credit cards; 0% with the ScotiaGold Passport Visa Card only | Canadian and international Visa and Mastercard; American Express not stated | Not stated; no landlord participation required | Not stated |
| TenantPay | 1.75% Visa credit; 2.75% Mastercard credit | Visa, Mastercard; American Express not supported | Direct deposit, typically within 1 to 3 business days | Optional; on-time payments reported to Equifax, free |
| RentMoola (now Letus) | Service fee charged on top of rent; amount not published | Visa, Mastercard, Amex, Discover, UnionPay logos shown | Through the platform; landlord or property manager must be a Letus partner | No bureau named on its site |
Sources: chexy.co, chexy.co/rentcashback, neobanc.com and its FAQ, paywithcasa.com and its help centre, help.scotiabank.com, tenantpay.com/pricing, tenantpay.com/earn, let.us tenant page and terms. Checked October 22, 2026. Fees can change; each service shows the fee before you confirm a payment.
Bilt and Plastiq come up in rent-by-card searches. Neither site showed us a rent product for Canadian renters, so they’re not in the table. We also left out platforms whose card fees we couldn’t confirm on their own pages.
Step 1 The service
Referral status can lower the Canadian-card fee; 1.75% is the standard rate. Charges your card 4 business days before rent is due.
Step 2 Your card and rent
- Service fee
- $35.00a month (1.75%), $420 a year
- Rewards earned
- $20.00a month, $240 a year (1% back)
- Net result
- −$15.00a month, −$180 a year
To break even, a card needs to return at least 1.75% on rent. This card returns 1% (counted as everyday spending).
Carry it instead of paying in full and one month of interest at 19.99% is about $33.32, more than most of the rewards above.
Chexy’s fees from its own site, checked 2026-10-22. Card earn rates and point values from our card data; the card’s annual fee isn’t included, since you’d pay it either way. Issuers decide how a rent payment is coded, so confirm it earns rewards (and isn’t treated as a cash advance) before you rely on these numbers.
Chexy rent payments: fees and how it works
Chexy charges a flat 1.75% per payment on Canadian-issued Visa, Mastercard and American Express cards, as of October 2026. International cards pay 2.5%. Your landlord still gets an e-Transfer, a bill payment or a pre-authorized debit, and doesn’t need to sign up.
Chexy charges your card 4 business days before rent is due, then sends the rent on rent day. It lists no minimum payment. Besides rent, its FAQ says it can pay utilities, taxes, condo fees, insurance, tuition, gym memberships and child care, as long as the payee accepts e-Transfer, bill payment or pre-authorized debit.
On $2,000 rent, Chexy’s 1.75% fee is $35 a month, or $420 a year. The site’s homepage says referral status can lower the fee for Canadian cards. We used the standard 1.75% in every calculation below.
Chexy’s own guide says you earn rewards once the charge has posted and is no longer pending on your card. How your card categorizes the charge is up to your issuer, not Chexy, which matters for the math later on.
Neobanc, Casa, TenantPay and Letus: other options
Neobanc is a rent and bill payment app that pays your landlord by Interac e-Transfer, so the landlord doesn’t need an account. Its pages disagree on the card fee: the homepage says 2.75% for Visa and Mastercard, while the FAQ says 1.50% to 2.25%. American Express isn’t supported, and each account can make one rent payment a month. It also offers opt-in rent reporting to credit bureaus without naming them.
Casa charges 1.75% on Canadian credit cards and 1% on debit cards, with 2.4% on international credit cards, as of October 2026. Casa waives its fee entirely for one card, the ScotiaGold Passport Visa Card. Scotiabank says the card is the only one that earns Scene+ points on rent through Casa, and only when you also spend $350 on other purchases that month. Casa isn’t available in Quebec. Its pages don’t say how the landlord is paid or whether payments are reported to a credit bureau, and we couldn’t confirm American Express acceptance.
TenantPay charges 1.75% on Visa credit and 2.75% on Mastercard credit, as of October 2026. Letus charges a service fee on top of rent but doesn’t publish the amount. Both are rent platforms, so check that your landlord or building can be paid through them.
TenantPay calls itself a loyalty program for renters. Its pricing page lists tenant fees by payment method: 1.75% for Visa credit, 2.75% for Mastercard credit, 0.99% for Visa and Mastercard debit, and a flat $4.99 for pre-authorized debit. It pays out by direct deposit, typically within 1 to 3 business days.
On $2,000 rent, that’s $35 a month by Visa credit and $55 by Mastercard credit. By debit it’s $19.80, and by pre-authorized debit $4.99. TenantPay’s June 8, 2026 guide says American Express and prepaid cards are not supported.
TenantPay’s pages aren’t consistent on landlord involvement. Its homepage says no landlord participation is required. Its June 2026 guide describes the card option as working if your property manager uses TenantPay. Ask TenantPay, and your landlord, before you count on it.
Letus is a rent platform for property managers. Typing rentmoola.com now lands on let.us, and Letus’s help centre and LinkedIn page still use the RentMoola name. Its tenant page shows Visa, Mastercard, Amex, Discover and UnionPay logos and says your property manager can invite you to set up your account.
Letus’s terms name PaySlate Inc. as the provider, under British Columbia law. They say a non-refundable service fee is charged in addition to each payment, and that Letus can change fees at its discretion. The amount isn’t on its public pages, so you’ll only see it at checkout.
Will my card treat rent as a purchase?
It can vary, and it’s the issuer’s call, not the service’s. Neither Chexy, TenantPay nor Letus says how issuers code their charges, and we found no Canadian issuer that publicly names them. Check with your issuer before a large payment.
This matters because cash advances are expensive. The Financial Consumer Agency of Canada (FCAC) says federally regulated issuers must give a grace period of at least 21 days on purchases, but the grace period doesn’t apply to cash advances, cash-like transactions or balance transfers. Interest on those runs from the day of the transaction.
The FCAC says issuers often treat some cash-like transactions as cash advances. Its examples are electronic wire transfers between institutions, money orders, travellers’ cheques and gaming transactions. A rent payment through a bill payment service isn’t on that list, but each issuer sets its own rules in its cardholder agreement.
Cash advance rates are higher, too. TD’s Cash Back Visa Infinite page, for example, lists 21.99% on purchases and 22.99% on cash advances. The FCAC notes a fee may apply as well, which would make the rent math far worse.
A second coding question affects rewards. Some cards pay more on recurring bills. TD defines recurring bill payments on its Cash Back Visa Infinite as payments “classified by the Visa payment network as recurring payments that are pre-authorized with a merchant.” Whether a rent service’s charge meets that definition depends on how the service processes it.
The math: fees vs. rewards on $2,000 rent
A card must return more than the fee to come out ahead. At a 1.75% fee, $2,000 rent costs $35 a month. A 1% card earns $20 back, so you lose $15 a month. Only cards that earn more than 1.75% on the rent charge itself make money.
The table runs $2,000 a month, or $24,000 a year, through a 1.75% fee and a 2.75% fee. The 1.75% column matches Chexy and TenantPay’s Visa credit fee. The 2.75% column matches TenantPay’s Mastercard credit fee. Rewards are shown as a cash value.
| Card return on rent | Rewards per month | Net per month at 1.75% fee | Net per year at 1.75% fee | Net per year at 2.75% fee |
|---|---|---|---|---|
| 1% | $20 | Lose $15 | Lose $180 | Lose $420 |
| 1.25% | $25 | Lose $10 | Lose $120 | Lose $360 |
| 1.5% | $30 | Lose $5 | Lose $60 | Lose $300 |
| 1.75% | $35 | Break even | $0 | Lose $240 |
| 2% | $40 | Gain $5 | Gain $60 | Lose $180 |
| 3% | $60 | Gain $25 | Gain $300 | Gain $60 |
| 4% | $80 | Gain $45 | Gain $540 | Gain $300 |
Fee: $35 a month ($420 a year) at 1.75%; $55 a month ($660 a year) at 2.75%. Assumes the balance is paid in full, no cash advance coding, and no earn cap. Points cards depend on what you value a point at.
Base earn rates of 1% to 1.5% are common in our card data. At those rates, paying rent by card loses $60 to $180 a year at the 1.75% fee. At 2.75%, even a 2% card loses $180 a year.
A 2% flat card gains $60 a year at the 1.75% fee. That’s real, but small: $5 a month, for the work of setting it up and the risk of a missed payment. The gains only become meaningful at 3% or 4%, which in practice means a bonus category that captures rent.
Earn caps change the answer. Many bonus categories stop after a set amount of annual spending. A year of $2,000 rent is $24,000 of spending, which is enough to run past several common caps, as the TD example below shows.
Real cards from our data, run through the math
Using our card data, only cards earning 2% or more on rent beat Chexy’s 1.75% fee, and only by $60 to $120 a year. Cards earning 1.25% to 1.5% lose money before you count their annual fee. Each example below is $24,000 of rent a year at 1.75%.
| Card | Annual fee | Earn rate that applies to rent | Rewards on $24,000 | Net after $420 fee |
|---|---|---|---|---|
| SimplyCash Card from American Express | $0 | 1.25% on everything else | $300 | Lose $120 |
| RBC Cash Back Preferred World Elite Mastercard | $120 | 1% (rent isn’t one of its 3% categories) | $240 | Lose $180 |
| Rogers Red World Elite Mastercard | $0 | 2% with an eligible Rogers, Fido, Shaw or Comwave service; 1.5% without | $480 (or $360) | Gain $60 (or lose $60) |
| SimplyCash Preferred Card from American Express | $119.88 | 2% on everything else | $480 | Gain $60 |
| TD Cash Back Visa Infinite Card | $139 | 3% on recurring bills, first $15,000 a year, then 1%, if rent codes as a Visa recurring payment | $540 (or $240 at 1%) | Gain $120 (or lose $180) |
Earn rates and annual fees from CreditLab’s product data and the issuers’ pages, October 2026. Net figures leave out the annual fee, which you pay for the whole card, not just for rent.
The SimplyCash Card from American Express earns 1.25% on everything that isn’t groceries or gas. Rent through Chexy earns $300 a year against a $420 fee. You’d be paying $120 a year for the convenience.
The RBC Cash Back Preferred World Elite Mastercard earns 3% on groceries, dining, gas, transit and streaming, but rent falls under everything else at 1%. That’s $240 a year against $420 in fees. Keep it for the 3% categories and pay rent another way.
The Rogers Red World Elite Mastercard and the SimplyCash Preferred Card from American Express both earn 2% on everyday purchases. On rent through Chexy, that’s $480 against $420, or $60 ahead a year. The Rogers card only pays 2% if you have an eligible Rogers, Fido, Shaw or Comwave service. Without one it’s 1.5%, and you lose $60.
The TD Cash Back Visa Infinite Card is the case where coding decides everything. If the rent charge counts as a Visa recurring payment, it earns 3% on the first $15,000 a year, which is $450, plus 1% on the other $9,000, which is $90. That’s $540 against $420, or $120 ahead. If it codes as an ordinary purchase, it earns 1%: $240, and you lose $180.
Rent also uses up the $15,000 cap that would otherwise go to groceries, gas, transit and other 3% categories on that card. If you already spend near the cap in those categories, the rent earns closer to 1%.
Welcome bonuses: when rent can pay off
Rent pays off most clearly when it helps you reach a new card’s welcome bonus that you wouldn’t hit otherwise. The bonus is often worth several months of fees. If your normal spending already reaches the minimum, rent adds nothing extra except the base earn rate, minus the fee.
Take the SimplyCash Preferred Card from American Express. Our data shows 10% cash back on the first $2,000 in purchases in the first 3 months, up to $200. One $2,000 rent payment through Chexy, which takes Amex, costs a $35 fee and earns the $200. That’s $165 ahead, before the card’s $119.88 annual fee.
TD’s Cash Back Visa Infinite page lists a 10% welcome rate on up to $3,500 of spending in the first 3 months, which is $350. Two rent payments total $4,000 and cost $70 in fees at 1.75%. That’s $280 ahead, plus whatever the last $500 earns at the normal rate.
| Card | Welcome offer | Rent used | Fee at 1.75% | Net |
|---|---|---|---|---|
| SimplyCash Preferred Card from American Express | 10% on the first $2,000 in 3 months, up to $200 | $2,000 (one month) | $35 | Gain $165 |
| TD Cash Back Visa Infinite Card | 10% on up to $3,500 in 3 months, $350 | $4,000 (two months) | $70 | Gain $280 |
Offers change and have conditions. Read the issuer’s current terms before applying. Net figures are before annual fees.
Points cards work the same way, with one more step: you need a value for each point. Our welcome bonus planner lays out the minimum spend and deadline for an offer, so you can see how many rent payments it would take.
Cash-flow timing is the other honest case. If you pay the card in full, the money for rent stays in your account until the card’s due date, which is at least 21 days after the statement. That can smooth a tight month. It doesn’t earn enough to cover the fee on its own.
The risks: interest, utilization and timing
The biggest risk is interest. If you don’t pay the card in full, purchase interest on $2,000 at 21.99% is about $36.65 for one month, more than the $35 fee. Carry it for longer and rent becomes an expensive loan.
21.99% is the purchase rate on several of the cards above in our data, including both SimplyCash cards and the TD Cash Back Visa Infinite. The FCAC also notes that missing your minimum payment by the due date can lead your issuer to raise your interest rate. Our credit card interest calculator shows what a carried balance costs over time.
- Can help you reach a welcome bonus minimum spend
- Earns more than the fee on a few cards with 2% or higher returns on rent
- Delays when the cash leaves your account if you pay the card in full
- Some services offer optional rent reporting to Equifax
- A 1.75% to 2.75% fee on every payment
- Most everyday earn rates are below the fee
- Interest at 21.99% on the cards above if you carry the balance
- Raises your reported card balance, and your utilization
- An extra party between you and your landlord, with its own timing
Credit utilization goes up. Equifax describes utilization as how much of your available credit you’re using, and notes issuers report your balance to the bureaus once a month. $2,000 of rent on a card with a $5,000 limit is 40% utilization from rent alone. On a $10,000 limit it’s 20%.
Fees can quietly eat your rewards. Fees run on every payment, every month, while bonus categories often have caps. Recheck the math once a year, and whenever your card or the service changes its terms.
Timing is the operational risk. A late rent payment is your responsibility under your lease, not the service’s. Chexy charges your card 4 business days ahead, and TenantPay says deposits typically take 1 to 3 business days. If a card is declined or a payee’s details change, rent can be late.
Landlord consent matters with platform services. With Letus, the landlord must be a Letus partner. With Chexy, the landlord receives a normal e-Transfer and isn’t asked to sign up, but a landlord who wants rent from your own bank account can say so in your lease.
Does paying rent by credit card build credit?
Not by itself. Paying your card on time is what builds credit, rent or no rent. Some services can also report your rent to a credit bureau if you opt in. As of October 2026, the ones that say so on their own sites report to Equifax only.
TenantPay’s pricing page says rent reporting is optional, and when it’s on, your on-time payments are reported to Equifax. Its earn page calls it free credit building on every on-time payment. TenantPay doesn’t mention TransUnion.
Chexy described an opt-in Credit Builder in a June 21, 2024 article. You turn it on in your account, accept the terms and upload your lease, and Chexy reports your rent payment history to Equifax. Chexy’s current homepage and FAQ don’t mention it or a price, so check in the app.
Letus’s tenant page says paying rent with a rewards card helps you build credit, but it doesn’t name a bureau or describe reporting. We left it as not stated.
Your card itself is reported every month whether rent is on it or not. Paying it on time and keeping the balance low relative to your limit are what count. For what lenders look at, see what a good credit score is.
How to pay rent with a credit card: steps
Run the math first, then confirm the card’s coding with one payment, then automate. Here’s the order that avoids the expensive mistakes.
- Check your card’s earn rate on this chargeFind the rate that would apply to a bill payment service, not your card’s headline rate. If it’s below the service’s fee, stop unless you’re working toward a welcome bonus.
- Pick a service your landlord can be paid throughChexy pays by e-Transfer, bill payment or pre-authorized debit. TenantPay and Letus pay through their platforms. Confirm your card network is accepted: TenantPay doesn’t take Amex.
- Read the fee on the confirmation screenFees can change. Make sure the percentage shown matches what you expect before you confirm.
- Send one test paymentWhen it posts, check that your statement shows a purchase, not a cash advance, and that it earned rewards at the rate you expected.
- Schedule it ahead of the due dateAllow for the service’s timing. Chexy charges 4 business days before rent is due; TenantPay deposits typically take 1 to 3 business days.
- Pay the card in full every monthSet up an automatic full-balance payment from your bank account so the rent never carries interest.
- Recheck once a yearEarn caps reset, welcome offers end and fees change. Rerun the numbers with your current card.
Cheaper alternatives to paying rent by card
Paying from your bank account costs less in nearly every case. An Interac e-Transfer, a pre-authorized debit or a cheque has no 1.75% fee. If your card doesn’t earn more than the fee, a bank payment leaves you ahead.
Many chequing account plans include e-Transfers, so check yours. TenantPay’s own fee for pre-authorized debit is a flat $4.99, which on $2,000 rent is far below its card fees.
If you want rewards on rent without the fee, put that effort into your other spending instead. A cash back card that matches what you already buy every month, like groceries or gas, often earns more than rent would after fees.
If what you really want is credit history from rent, you don’t need a credit card for that. TenantPay lists Equifax reporting alongside its debit and pre-authorized debit options, and Chexy’s article says it doesn’t need to contact your landlord to report.
Frequently Asked Questions
Can you pay rent with a credit card in Canada?
Yes, but usually through a third-party service rather than your landlord. Chexy, TenantPay and Letus charge your card and pay your landlord by e-Transfer, debit or deposit. You pay a fee on top of rent, 1.75% at Chexy as of October 2026. A few property managers take cards directly through their own rent platforms.
What does Chexy charge to pay rent?
As of October 2026, Chexy charges a flat 1.75% per payment on Canadian-issued Visa, Mastercard and American Express cards, and 2.5% on international cards. On $2,000 rent, that’s $35 a month or $420 a year. Chexy lists no minimum payment, and its homepage says referral status can lower the fee.
Does paying rent with a credit card count as a cash advance?
It depends on your issuer. Rent services don’t say how issuers code the charge, and no Canadian issuer we checked names them publicly. The FCAC lists wire transfers, money orders and gaming as cash-like transactions often treated as cash advances. Make one small test payment and check your statement before paying full rent.
Does paying rent with a credit card build credit?
Not on its own. Paying your card on time is what helps. Some services also report rent if you opt in: TenantPay reports on-time payments to Equifax, and a 2024 Chexy article describes Credit Builder reporting to Equifax. Neither says it reports to TransUnion.
Is paying rent with a credit card worth it for rewards?
For most cards, no. At a 1.75% fee, a 1% card loses $180 a year on $2,000 rent, and a 1.5% card loses $60. A 2% card gains $60 a year. It’s clearly worth it mainly when rent helps you reach a welcome bonus you’d otherwise miss.
Can my landlord refuse credit card rent payments?
With Chexy, your landlord receives an ordinary e-Transfer, bill payment or pre-authorized debit and isn’t asked to sign up. Platform services are different: Letus only pays landlords and property managers that are Letus partners. Your lease sets how rent must be paid, so check it.
Can I pay rent with an American Express card?
Yes, through some services. Chexy accepts Canadian-issued American Express cards at the same 1.75% as Visa and Mastercard, as of October 2026. TenantPay says American Express isn’t supported. Letus shows the Amex logo on its tenant page but doesn’t publish its fee.
What happens if my rent payment through a service is late?
Your lease is with your landlord, so a late payment is your responsibility, not the service’s. Leave room for the service’s timing: Chexy charges your card 4 business days before rent is due, and TenantPay deposits typically take 1 to 3 business days. Contact the service and your landlord right away.
What is the cheapest way to pay rent with a credit card?
Among the services we checked, the lowest published card fee was 1.75%, at both Chexy and TenantPay’s Visa credit option, as of October 2026. TenantPay charges 2.75% on Mastercard credit. Letus doesn’t publish its fee. A bank e-Transfer or pre-authorized debit costs less than any card option.
Try this next
Sources, checked October 2026
- Chexy: homepage, pricing and FAQ chexy.co
- chexy.co chexy.co
- Chexy: pay rent and earn cash back chexy.co
- Chexy: How to pay rent with a credit card in Canada (December 30, 2025) chexy.co
- Chexy: How to report rent payments and build your credit score (June 21, 2024) chexy.co
- TenantPay: homepage tenantpay.com
- TenantPay: pricing tenantpay.com
- TenantPay: how you earn tenantpay.com
- TenantPay: pay rent with a credit card in Canada (June 8, 2026) tenantpay.com
- Letus: tenants let.us
- Letus: terms of use let.us
- Financial Consumer Agency of Canada: How credit cards work canada.ca
- TD Cash Back Visa Infinite Card td.com
- Equifax Canada: What is credit utilization? equifax.ca
- Neobanc homepage neobanc.com
- Neobanc FAQ neobanc.com
- Casa homepage and fees paywithcasa.com
- Scotiabank: How is Scotiabank working with Casa? help.scotiabank.com
General information for Canadians, not financial, tax or legal advice. Rules and menus change, so confirm details with your bank, lender or the Government of Canada. See our methodology.